

PROPERTY INVESTOR GUIDE
The First Investment Property Guide NZ
Plenty of Kiwis own one rental. Far fewer own one that performs. The difference is the numbers you ran before you bought and the way you structured the debt. This free guide covers both.
Advice at no cost to you
Auckland, Wellington, Christchurch
What is Inside
01
How much you actually need
02
Using equity in your home instead of cash
03
Gross yield vs net yield
04
Cashflow: positive, neutral or negative
05
Loan structure for investors
06
Interest only, and when it makes sense
07
Tax basics to know before you buy
08
The investor checklist
You Probably do Not Need Cash for the Deposit
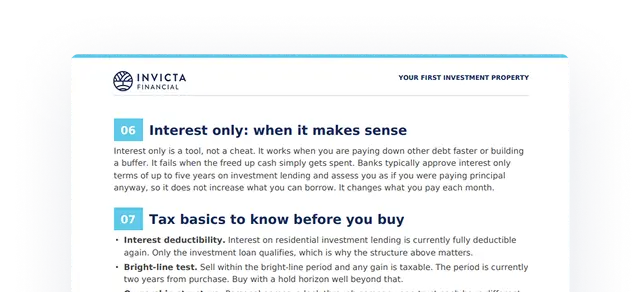
Interest deductibility, bright-line and ownership structure all move your return, and they change with governments. The guide lists what to check, and we bring an accountant into the conversation.
Gross Yield is What Agents Quote. Net Yield is What Pays Your Bills.
Same property, and the real return can be half the number on the listing.
The guide has the full worked example line by line so you never buy on the wrong figure.
Loan Structure Separates Investors From Landlords With a Hobby
Most first time investors let the bank lump everything into one loan and pay for it for years. The guide compares weak structure against strong structure in one table.
You Probably do Not Need Cash for the Deposit
Most first time investors fund the deposit from equity they already have in their home. The guide shows the usable equity calculation and what a typical home can actually support.
Get the Full Investment Property Guide Sent to You
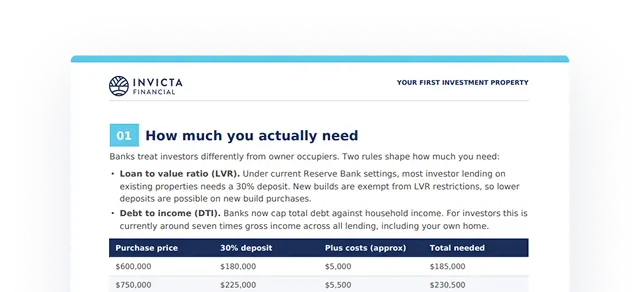
Deposit tables, the usable equity calculation, a full net yield worked example, and the loan structure comparison. In your inbox in a minute.

Why Clients Choose Us
Putting people first, every step of the way
I want to thank Andrew Liu for all his help — honestly can’t recommend him enough. Super professional and really knows his stuff — you can tell right away he’s not just winging it. He takes the time to actually explain things instead of just throwing numbers at you. If you’re looking for someone reliable to help with your finances, Andrew’s your guy.
Andre B
Orion Chau was great to work with, very informative and found a more affordable insurance provider. It was a pleasure to work with Orion and Lily.
Melissa P
I was frustrated with our previous broker and reached out to Connor. Not only did he find us a better policy, he was great to deal with especially considering he had to work around our busy schedule. Thanks again.
Russell E
I highly recommend Richard Moore for his exceptional professionalism, deep knowledge, and absolute honesty. I reached out to him to review my income protection insurance and explore other financial options.Instead of just trying to sell me a new policy, Richard conducted a meticulous, detailed comparison between my current provider and the market alternatives. He concluded that my existing coverage was already excellent and honestly advised me to stick with it.Finding an adviser who prioritizes the client's best interests over making a sale is rare. Richard has earned my complete trust, and I will absolutely look to him for all my future insurance and financial planning needs.
Sau Lee C
5/5 Stars ~ Working with Paige (Financial Advisor) at Invicta Financial has been such a great experience. Right from the start, she was incredibly nice and so easy to talk to. She really went above and beyond to make sure I was looked after, and I genuinely appreciate everything she’s done for me. If you’re looking for someone who actually cares, definitely reach out to her!
Kayla S
Tom has been a dream to deal with! Very easy to communicate with.
Debra S
Dealt with Caleb to sort my KiwiSaver, he was very professional, helpful and warm. He helped me switch from my standard bank over to an externally managed fund, and I have seen positive growth in my KiwiSaver. A very knowledgeable advisor.
Tayla W
Investment Property Questions, Answered
Interest on residential investment lending is currently fully deductible. Only the investment loan qualifies, which is why keeping loans separate matters. Confirm current settings with your accountant.
Often yes. Interest only on the rental maximises cashflow and keeps deductible debt high while you pay down your own home loan faster. Banks assess you as if you were paying principal anyway.
Focus on net yield, not gross. Net yields on standard residential property in the main centres are commonly between 2% and 4% after all costs. What counts as good depends on your cashflow position and growth expectations.
Yes. Banks generally let you borrow against 80% of your home’s value. The difference between that and your current mortgage is usable equity, which can fund the deposit and costs on an investment property.
Under current Reserve Bank rules most investor lending on existing properties needs a 30% deposit. New builds are exempt, so lower deposits are possible on new build purchases.
More Free Guides
Want to See Your Numbers Before You go Looking?
Send us your home value, mortgage and income. We show you usable equity, borrowing power, and how we would structure it.